Author: UK Smart Money Team

  • Holiday Budget Calculator UK 2026 – How Much Will Your Trip Cost?

    Holiday Budget Calculator UK

    Work out the real cost of your holiday and how much to save every payday before you fly.

    Your trip

    Main costs

    £

    £

    £

    Extras people forget

    £

    £

    £

    £
    Your savings

    £

    Total holiday cost

    £0

      £0Save per payday
      £0Cost per person
      £0Cost per night

      Want to bring that total down? Flights and accommodation are usually the biggest costs, so compare prices before you book.

      How to use this holiday budget calculator

      Enter who is travelling, how many nights you will be away and when you leave. Add your flight and accommodation prices, then a daily spending budget for food, drinks and days out. Do not skip the extras section: travel insurance, airport parking, hold luggage and car hire can add hundreds of pounds to a trip that looked cheap when you first saw the price.

      The calculator shows your full holiday cost, where the money goes, and exactly how much to put aside every payday so the holiday is paid for before you fly, not sitting on a credit card when you get home.

      7 ways to cut the cost of your holiday

      1. Compare flights across dates

      Flying a day earlier or later, or midweek instead of at the weekend, can make a big difference to the price. Always check a few dates before you book.

      Search cheap flights

      2. Compare accommodation prices before you book

      The same hotel can be listed at different prices, with different free-cancellation terms. Compare a few options and read what is included, such as breakfast or city taxes.

      Check hotel prices

      3. Book airport parking in advance

      Turning up and paying at the gate is almost always the most expensive option. Pre-booking, or comparing it with a taxi or train, usually saves money.

      4. Buy travel insurance when you book

      Buying cover as soon as you book means you are protected if you have to cancel. An annual policy can be cheaper if you travel more than once a year.

      5. Travel light

      Hold luggage fees are charged per bag, per flight. Sharing one suitcase between two people or packing cabin-only can cut the cost noticeably.

      6. Use a card with no foreign transaction fees

      Many UK debit and credit cards add a fee every time you spend abroad. A fee-free travel card means more of your spending money goes on the holiday.

      7. Earn cashback on your booking

      Booking through a cashback site can put a percentage of what you spend on hotels and flights back in your pocket.

      Frequently asked questions

      How much spending money do I need per day?

      It depends heavily on the destination and your style of travel. Look at typical prices for meals and drinks where you are going and set a daily figure you are comfortable with. The calculator lets you set a lower budget for children.

      When is the best time to book a summer holiday?

      Many UK holidaymakers book in the new year, when travel companies run big January offers. Booking early also gives you more months to save.

      Is my data saved?

      No. Everything is calculated in your browser and nothing you type is stored or sent anywhere.

      This page contains affiliate links. If you book through them, UK Smart Money may earn a small commission at no extra cost to you. This calculator gives estimates for guidance only and is not financial advice.

    • Christmas Savings Calculator UK 2026 | UK Smart Money

      Christmas Savings Calculator UK 2026

      Christmas Savings Calculator UK

      … until Christmas Day. Add your gifts and see exactly what to put aside every payday.

      Who are you buying for?
      Other Christmas costs
      £
      £
      £
      £
      Your savings
      £

      £0 per payday

      £0Total Christmas cost
      £0Still to save
      £0Per day

      How to use this Christmas savings calculator

      List everyone you plan to buy for and what you want to spend on each person, then add the other costs that catch most people out: the food shop, decorations, travel and cards. Enter anything you have already put aside and choose how often you get paid. The calculator counts the paydays left before 25 December and tells you exactly how much to move into savings each time.

      Breaking the total into payday-sized amounts is the easiest way to avoid a January overdraft or a credit card bill you are still paying off in spring.

      5 ways to make your Christmas budget go further

      1. Set up a standing order on payday

      Move your per-payday amount into a separate easy-access savings pot the same day your wages land. Money you never see in your current account is much harder to spend.

      2. Earn cashback on everything you already buy

      Buying gifts through a cashback site or a card that pays cashback puts part of your spending straight back in your pocket. On a typical family Christmas that can be enough to cover a gift or two.

      3. Use voucher codes before you check out

      Always search for a live discount code before paying online. Big retailers run regular Christmas offers, and stacking a code with cashback doubles the saving.

      4. Shop the big sale events early

      Black Friday and early-November deals are often the lowest prices before Christmas. Buy from your list, not from the adverts.

      5. Agree limits with family

      A Secret Santa or a set spend per person can cut hundreds of pounds from the total, and most people are relieved when someone suggests it.

      Frequently asked questions

      How much does the average UK household spend at Christmas?

      Spending varies a lot by household size and income, which is why a personal budget built from your own gift list is far more useful than a national average.

      When should I start saving for Christmas?

      The earlier the better. Starting in January spreads the cost over twelve months, but even starting in autumn is much better than paying for everything in December.

      Is my data saved?

      No. Everything is calculated in your browser and nothing you type is stored or sent anywhere.

      This page contains affiliate links. If you buy through them, UK Smart Money may earn a small commission at no extra cost to you. This calculator is for guidance only and is not financial advice.

    • Mozillion iPhone 18 Pro Deals: What They Actually Cost Over 24 Months

      Prices checked: 18 September 2026  |  Reading time: about 9 minutes

      Affiliate disclosure: This article contains affiliate links to Mozillion. If you click one and go on to buy, we may earn a commission at no extra cost to you. It does not change the price you pay, and it did not change what we found. Every figure below was read from Mozillion’s own plan selector on 18 September 2026, and all the 24-month totals are our own calculations.

      Mozillion is selling the iPhone 18 Pro and 18 Pro Max on 24-month contracts with no mid-contract price rises — a real difference in a market where most networks raise your bill every April.

      But a fixed price is not the same as a good price. So we worked out the total cost across the full 24 months on every data tier, then checked it against buying the handset from Apple and adding a SIM-only plan instead.

      This is where the biggest difference in total cost appears — and it turns on something most people never think about: how much mobile data you actually use.

      A note on prices. This is a launch-week product and Mozillion’s prices have already moved once since release. Every figure here is a snapshot taken on 18 September 2026, not a live feed. Check the current price on the product page before ordering — the method in this article matters more than the specific numbers.

      The short version

      • Mozillion iPhone 18 Pro, 256GB: from £59.13 a month plus £29 upfront — £1,448.12 over 24 months on the 30GB plan
      • Mozillion iPhone 18 Pro Max, 256GB: from £63.88 a month plus £29 upfront — £1,562.12 over 24 months on the 10GB plan
      • On the 10GB plans, buying the handset from Apple and adding a SIM-only plan worked out cheaper — by £86 on the Pro and £72 on the Pro Max
      • On 100GB and unlimited, the bundled contract came out cheaper — by up to £142
      • Odd but true: on the iPhone 18 Pro, the 10GB plan costs more per month than the 30GB plan
      • Compare Mozillion’s SIM-free price against Apple’s before buying outright — when we checked there was £200 between them on the Pro Max

      Mozillion iPhone 18 Pro contract prices

      All figures are 256GB, 24-month contract, £29 upfront, on the EE network with unlimited calls and texts.

      Mozillion iPhone 18 Pro, 256GB, 24 months, £29 upfront. Totals are our calculation. Checked 18 September 2026 and subject to change.
      Data Monthly Total over 24 months
      30GB £59.13 £1,448.12
      10GB £60.29 £1,475.96
      100GB £61.29 £1,499.96
      Unlimited £66.79 £1,631.96
      Check the order of that table again. The 10GB plan costs £1.16 a month more than the 30GB plan. Over 24 months that is £27.84 extra for a third of the data. If you were going to take the 10GB tier on the iPhone 18 Pro, take 30GB instead — it is cheaper and gives you more. We confirmed this on the plan selector rather than assuming it was a display error.

      Mozillion iPhone 18 Pro Max contract prices

      Mozillion iPhone 18 Pro Max, 256GB, 24 months, £29 upfront. Totals are our calculation. Checked 18 September 2026 and subject to change.
      Data Monthly Total over 24 months
      10GB £63.88 £1,562.12
      30GB £64.38 £1,574.12
      100GB £64.88 £1,586.12
      Unlimited £72.88 £1,778.12

      Here the tiers rise in the order you would expect, and the steps are tiny: 10GB to 100GB costs £1 a month, or £24 across the whole contract. Unlimited costs another £8 a month, which is £192 over two years.

      That compression matters, and it is the key to the next section.

      Check the live prices

      Launch pricing moves. These go straight to Mozillion’s plan selectors, where you can pick storage, colour, data tier and upfront amount and see today’s figure.

      iPhone 18 Pro contract →

      iPhone 18 Pro Max contract →

      Affiliate links — we may earn a commission if you buy. Whatever the current price, do the same sum: monthly times 24, plus the upfront.

      Apple iPhone 18 Pro in black, showing front and back
      The iPhone 18 Pro. The Pro Max shares the same design and cameras — what differs is screen size, battery and price.

      Both models run the A20 Pro chipset with three 48MP cameras, and support nano-SIM and eSIM. The Pro has a 6.3in display, the Pro Max 6.9in. Beyond size and battery life, you are choosing between them on price rather than capability.

      Contract, or buy the phone and add a SIM?

      Mozillion sells SIM-only plans separately, with no credit check and the same fixed-price policy. So you can buy the handset outright from Apple and add a SIM instead of taking a bundled contract.

      Apple’s own starting prices are £1,199 for the iPhone 18 Pro and £1,299 for the Pro Max, both 256GB. Here is how the two routes compared on the figures we checked.

      iPhone 18 Pro, 256GB. Outright route is Apple at £1,199 plus 24 months of Mozillion SIM-only at the matching tier. Our own calculations from prices checked 18 September 2026.
      Data Mozillion contract Apple + SIM-only Cheaper on these figures
      10GB £1,475.96 £1,389.80 Outright, by £86
      30GB £1,448.12 £1,461.80 Contract, by £14
      100GB £1,499.96 £1,533.80 Contract, by £34
      Unlimited £1,631.96 £1,773.80 Contract, by £142
      iPhone 18 Pro Max, 256GB. Outright route is Apple at £1,299 plus 24 months of Mozillion SIM-only. Our own calculations from prices checked 18 September 2026.
      Data Mozillion contract Apple + SIM-only Cheaper on these figures
      10GB £1,562.12 £1,489.80 Outright, by £72
      30GB £1,574.12 £1,561.80 Outright, by £12
      100GB £1,586.12 £1,633.80 Contract, by £48
      Unlimited £1,778.12 £1,873.80 Contract, by £96

      At the lower data tiers, Apple plus SIM-only is cheaper. At the higher tiers the bundled contract is cheaper. The crossover falls at 30GB on the Pro and somewhere between 30GB and 100GB on the Pro Max.

      Why it flips. On contract, the data tiers barely differ — on the Pro Max, 10GB to 100GB costs £1 a month. On SIM-only, the same jump costs £6 a month. So the more data you need, the better value the bundle becomes. If you barely use data, a contract can mean paying for an allowance you will never touch.

      Another way to see it: at 100GB the handset works out at about £1,165 inside the iPhone 18 Pro contract, against Apple’s £1,199 — and about £1,251 inside the Pro Max contract, against Apple’s £1,299. At those tiers you are effectively getting the phone slightly below Apple’s price, spread across 24 months.

      Bear in mind that “cheaper” here means cheaper in pounds over 24 months, and nothing else. Buying outright also gives you ownership from day one, no credit agreement, and the freedom to change airtime provider whenever you like. Those may matter more to you than the difference in total.

      Mozillion SIM-only prices

      SIM-only plans, unlimited calls and texts with EU roaming on every tier, no credit check. Checked 17 September 2026 and subject to change.
      Data 24-month 12-month
      3GB £4.50 £4.70
      10GB £7.95 £8.50
      30GB £10.95 £11.50
      80GB £12.95 £13.50
      100GB £13.95 £14.50
      Unlimited £23.95 £24.50

      The 12-month plans cost between 20p and 55p a month more. The shorter term lets you reassess sooner, though it also means your price is only fixed for a year rather than two.

      If you are buying the handset outright

      Compare Mozillion’s SIM-free price against Apple’s before ordering. When we checked, Mozillion listed the iPhone 18 Pro Max 256GB at £1,499 while Apple’s own starting price for the same model was £1,299 — a £200 difference on identical hardware.

      Prices move, so check both. But it is a useful reminder that a retailer can be competitive on contracts and SIM-only while being expensive on outright sales. Check each separately rather than assuming one follows the other.

      What the plans include

      Unlimited calls and texts, 4G and 5G with a fair-use policy that allows throttling above 500GB a month, WiFi calling, hotspot tethering, spend capping so you cannot run up a surprise bill, and roaming across 41 European countries with up to 25% of your monthly allowance usable abroad.

      Mozillion runs on EE’s network, which it promotes as the UK’s best network based on industry awards — check coverage at your own address rather than taking that at face value. Handset contracts are 24-month credit agreements arranged through Affirm, with Mozillion acting as credit broker rather than lender, so they involve a credit check. SIM-only plans do not.

      There is also a scheme called Kill Your Bill, where you buy gift cards through their app for shops you were using anyway and a reward is credited against your phone bill. Mozillion states that most users reach a zero bill within their first month. We have not tested that, and how much it reduces your bill depends entirely on how much you spend and where, so treat it as a possible extra rather than a reason to choose the plan.

      Which route suits you

      Three situations, and the arithmetic points somewhere different in each.

      You have the cash and use little data

      Buy the handset from Apple and add a Mozillion SIM-only plan. On the figures we checked, the Pro Max at 10GB came to £1,489.80 all in over two years, around £72 less than the equivalent contract, and the Pro came to £1,389.80, around £86 less. You also own the phone outright, avoid a credit agreement, and can switch airtime whenever you like.

      You have the cash but want a lot of data

      Run both numbers before deciding. At 100GB the contract came out £34 cheaper on the Pro and £48 cheaper on the Pro Max, because the bundled data is priced so low. On the unlimited tiers the gap widened to £142 and £96. At those levels the contract is clearly the cheaper route in pounds, though you are trading ownership and flexibility for it.

      You do not have the full handset price spare

      The contract spreads the cost over 24 months, and the fixed-price policy means the payment you agree is the payment you make for the full term. That is worth something in a market where most contracts rise annually.

      Or consider last year’s model

      Worth thirty seconds before you commit. Mozillion also lists the iPhone 17 Pro Max and 17 Pro at lower monthly prices than the 18 series, for hardware one generation behind. If the newest chipset will not change how you actually use your phone, check both before deciding.

      How to check any phone deal yourself

      This is the part worth keeping, whoever you buy from. Four steps, five minutes, and it works on every contract you will ever be offered.

      1. Work out the total. Monthly payment times the number of months, plus anything upfront. That single number is the only fair way to compare two deals.
      2. Add the price rises. If a contract raises prices annually, work out what that adds across the term. A £2.50 monthly increase applied each April adds roughly £55 over 24 months; a percentage-based rise on an expensive plan can add considerably more. Check the specific terms of the contract in front of you.
      3. Split the phone from the airtime. Look up the handset price from the manufacturer, then a SIM-only plan with the same data, and add them together. Compare that against the contract total. If the contract is higher, you now know exactly what the convenience of spreading the cost is costing you.
      4. Check your real data use. Your phone settings or your current bill will tell you. Contract data tiers are often priced so the largest allowance looks almost free, which makes it easy to pay for data you never use.
      The habit that saves the most: never compare on the monthly figure. It is the number every advert leads with, precisely because it is the smallest and most flattering. The total is what leaves your account.

      Check the current prices

      Prices and availability shift, particularly around a launch. These links go to Mozillion’s contract pages, where you can choose storage, colour and data tier and see the live monthly figure for yourself.

      iPhone 18 Pro deals →

      iPhone 18 Pro Max deals →

      Affiliate links — we may earn a commission if you buy. Our advice stands either way: multiply the monthly by the term, add the upfront, and compare that total against the handset price plus a SIM-only plan before you commit.

      Frequently asked questions

      Is it cheaper to buy the phone outright?

      It depends on how much data you need. On the prices we checked, buying the Pro Max from Apple at £1,299 and adding a £7.95 SIM-only plan came to £1,489.80 over two years, around £72 less than the 10GB contract. At 100GB the contract came out £48 cheaper, and on unlimited £96 cheaper, because bundled data is priced very low. Work out both figures for your own usage and current prices.

      Does Mozillion really not raise prices mid-contract?

      Mozillion states that payments are fixed with no mid-contract increases, and this applies to both handset contracts and SIM-only plans. That is a real difference from most UK networks, which raise bills each April. Confirm it in the plan terms before you sign, as with any contract commitment.

      How much do annual price rises actually cost?

      It depends on the contract. A flat increase of £2.50 a month applied each April adds roughly £55 across a 24-month term that starts in autumn. Percentage-based increases on a higher monthly payment can add considerably more. Check the specific wording of any contract you are offered.

      Which network does Mozillion use?

      Mozillion runs on EE’s network, so coverage matches EE rather than being separate. Check coverage at your own address with their coverage checker before ordering.

      Do SIM-only plans need a credit check?

      No. SIM-only plans have no credit check. Handset contracts do, because they are 24-month credit agreements arranged through Affirm, with Mozillion acting as credit broker rather than lender.

      How much data do I actually need?

      Check your current usage in your phone settings or on your bill rather than guessing. On the SIM-only prices we saw, 10GB was £7.95 and 100GB was £13.95, so the larger tier costs £144 more across two years — worth it if you use it, wasted if you do not. On contract the same step costs as little as £24, which is why the bundle wins at the top tiers.

      How much storage should I get?

      Check how much you are using on your current phone, in Settings. Larger storage adds several hundred pounds across a 24-month term, so it is worth knowing whether you need it before paying for it.

      What should I do when the contract ends?

      Move to a SIM-only plan. You own the phone at that point, so staying on contract pricing means paying for a handset you already own. Set a calendar reminder — this is one of the most common ways people quietly lose money on mobile contracts.

      The verdict

      Mozillion’s fixed-price policy is real and unusual, and worth having in a market where most contracts rise every April. The plans themselves are well specified: EE coverage, generous data, spend capping and proper European roaming.

      The decision that moves the most money is contract versus outright, and it turns on your data use rather than your bank balance. On the figures we checked, on the 10GB tiers buying the handset from Apple and adding a cheap SIM-only plan came out £72 to £86 cheaper. At 100GB and above the bundled contract was cheaper, by £34 to £142 depending on model and tier. And if you are buying outright, compare Mozillion’s SIM-free price against Apple’s first — when we looked there was £200 between them.

      Whatever you choose, do the arithmetic on the day you buy. Multiply the monthly by the term, add the upfront, and compare that total. Prices on a launch product move quickly, and the total is the only number that tells you the truth about a phone deal.


      Sources and method

      Contract prices, SIM-only prices, SIM-free prices, plan inclusions, roaming terms, credit terms and delivery dates were taken from Mozillion’s own product and plan pages on 17 September 2026. Apple SIM-free prices as published for the UK launch, September 2026. All 24-month totals are our own calculations from those figures. Mozillion is a launch-week retailer on a newly released handset and its prices may have changed since we checked — the figures here are a dated snapshot, not a live price feed, and you should confirm current prices on the retailer’s own pages before ordering.

      This article is general information, not financial advice. Always confirm current prices and contract terms directly with the retailer before buying.

    • Blue Ape Renewables Review 2026: Pricing, Accreditations and the Small Print

      Reviewed: September 2026  |  Reading time: about 10 minutes

      Affiliate disclosure and how we reviewed this. We have an affiliate arrangement with Blue Ape Renewables, meaning we may earn a commission if you request a quote through our links and go on to buy. That is why we have been explicit below about what we could and could not verify. This review is based on published pricing, accreditation records, finance documentation and publicly visible customer reviews as of September 2026. We have not installed a system ourselves and we have not been paid to write a positive review. Where we think something is worth questioning, we have said so.

      Most UK solar installers will not tell you what anything costs until a salesperson has been to your house. Blue Ape Renewables publishes a price list. That single fact makes them worth reviewing properly, because it lets you do something you usually cannot do in this industry: compare a real number against the market before anyone gets your phone number.

      So this review does exactly that. We take their published prices, work out the cost per kilowatt-peak, compare it against national averages, run a payback calculation on their entry package, and go through the finance small print. Then we look at the accreditations, the warranty terms, and the things we think you should ask them directly.

      Verdict in brief

      Blue Ape Renewables is a Southport-based, family-run installer covering England, Scotland and Wales, with an unusually complete accreditation stack — MCS, NAPIT, RECC, TrustMark, Tesla Certified and GivEnergy approved among others — and a Trustpilot rating of 4.9 across 70-plus reviews.

      What genuinely stands out: published fixed pricing, a £200 fully refundable deposit, a detailed public list of what is not included, and a repairs division that services systems other companies installed.

      What to scrutinise: the headline £5,150 is for a small 2.73kWp system, so the cost per kWp is above the national average; the standard workmanship warranty is two years, which is on the short side; and one of the two finance options is considerably more expensive than it first appears.

      Best suited to: homeowners who want a transparent, no-haggle price and value accreditation depth over the lowest possible quote. As with any installer, they should be one of at least three quotes you compare.

      Who are Blue Ape Renewables?

      Blue Ape Renewables is a renewable energy installer based at Hall Street in Southport, PR9 0SE, trading as BlueApe Limited. The business describes itself as family-run, with over 40 years of combined management experience in the sector, and installs across England, Scotland and Wales.

      Their range is broader than solar alone:

      Published starting prices, September 2026. Starting prices reflect entry-level configurations; your quote depends on survey.
      ServiceFrom
      Solar PV (6-panel, 2.73kWp)£5,150
      Solar PV + 3.2kWh battery£6,615
      Battery storage (standalone)£1,465
      Air source heat pump£3,850 after the £7,500 Boiler Upgrade Scheme grant
      EV charger£805
      Solar carport£10,155
      Commercial solar (50kW)£51,950
      Inverter repair / replacement£250

      One detail worth flagging early: they repair and service systems they did not install, including diagnostics on older inverters and relocating equipment out of hot loft spaces. That is not a headline-grabbing service, but it signals technical depth. Companies that only fit new systems tend not to build a repairs function.

      The pricing, analysed properly

      Here is where publishing a price list becomes genuinely useful. We can do arithmetic that is normally impossible before a sales visit.

      What £5,150 actually buys

      The entry package is 2.73kWp: six DMEGC 455W panels with a Hanchu hybrid inverter, including smart monitoring, a bird deterrent, one elevation of scaffolding up to 8m, MCS registration, DNO notification, commissioning and handover.

      That works out at £1,886 per kWp.

      Government MCS data put the national average at around £1,785 per kW for systems in the 4–10kW range as of June 2026. So on the face of it, Blue Ape’s entry package is roughly 6% above average.

      But that comparison is not quite fair, and it is worth understanding why, because the same distortion appears in every quote you will receive.

      Small systems always cost more per kWp. Scaffolding, the inverter, the electrician’s day, the DNO paperwork and the MCS registration cost roughly the same whether you fit six panels or fourteen. Spread those fixed costs over 2.73kWp instead of 4kWp and the per-unit price inevitably rises. A 2.73kWp system at £1,886/kWp is not evidence of overcharging — it is what a small system costs. The lesson is the reverse of what most people assume: if your roof can take more panels, the extra panels are the cheapest part of the whole job.

      The practical consequence is that if you want 4kW or more — which is the size most three-bedroom homes should be looking at — you fall into their “Custom Solar Solutions” tier, which has no published price. So the transparency advantage partly evaporates at exactly the system size most people need. Worth knowing before you assume the price list covers you.

      The battery increment is the interesting number

      Moving from the PV-only package at £5,150 to the PV-plus-battery package at £6,615 costs £1,465 for 3.2kWh of Hanchu storage. That is roughly £458 per kWh installed.

      For context, the wider market for residential battery storage generally runs from around £3,000 to £8,000, with typical installed costs frequently landing well above £600 per kWh. On a pure pounds-per-kilowatt-hour basis, that increment is competitive.

      The caveat is size. 3.2kWh is a small battery. It will comfortably carry a household’s baseline evening load — lights, fridge, TV, router — for a few hours. It will not run an electric shower, an oven and a tumble dryer through a winter evening. If you are buying storage to meaningfully shift your consumption, or to charge cheaply overnight and discharge through the peak, you will want considerably more capacity, and you are back in custom-quote territory.

      Does the entry package actually pay back?

      Let us run it. A 2.73kWp system in an average English location generates roughly 2,300 kWh a year. We will use 26.32p per kWh for grid electricity — Ofgem’s price cap rate for 1 October to 31 December 2026 — and a realistic 12p per kWh export rate.

      Our own calculation using Blue Ape’s published prices and current Ofgem rates. Illustrative — your consumption pattern will change these figures substantially.
      PV only (£5,150)PV + 3.2kWh battery (£6,615)
      Annual generation~2,300 kWh~2,300 kWh
      Assumed self-consumption35%55%
      Grid electricity avoided805 kWh = £2121,265 kWh = £333
      Exported at 12p1,495 kWh = £1791,035 kWh = £124
      Total annual benefit~£391~£457
      Simple payback~13 years~14.5 years

      Two honest observations.

      First, a 13-year payback on the PV-only package is unremarkable — normal for a small system, and longer than the 9–11 years typical of a well-sited 4kW installation. Again, that is the small-system effect, not a criticism of the installer.

      Second, and more importantly: the battery adds £1,465 and returns about £66 a year on our assumptions. That is a payback measured in decades against a battery warranty measured in years.

      This matters because Blue Ape’s own FAQ says battery storage is “strongly recommended.” We would put it differently: a battery is worth it when it is doing more than storing surplus solar — charging overnight on a cheap off-peak tariff, discharging through the expensive evening peak, or exporting into a high time-of-use rate. Bought purely to store daytime solar on a flat tariff, small batteries rarely justify themselves on arithmetic alone.

      To be fair to them, their public customer reviews include one from someone who was advised against buying a battery after the team reviewed their bills and concluded their solar use was already well balanced. That is a meaningful signal, and more or less the opposite of what the industry is known for. But it is a reason to have the conversation with numbers in hand, not to skip it.

      Want to see their actual price for your roof?

      Their online quote tool gives a starting price in a few minutes without a sales visit, and the £200 deposit that locks in pricing is fully refundable if you decide not to proceed.

      Get a free Blue Ape quote →

      Affiliate link — we may earn a commission. Our advice is unchanged either way: get three quotes and compare them on predicted annual kWh and full specification, not headline price.

      Accreditations: what each one actually does for you

      Blue Ape lists an unusually long set of accreditations. Logos are easy to display, so here is what each one means in practice and where you can verify it independently.

      Accreditations listed by Blue Ape Renewables as of September 2026, with what each provides. Verify current status on each body’s own register before signing.
      AccreditationWhat it means for you
      MCS The important one. Without MCS certification, most suppliers will not put you on a Smart Export Guarantee tariff, and you cannot access grant-funded schemes. This is not a marketing badge — it directly determines whether you get paid for exported electricity.
      TrustMark Government-endorsed quality scheme, with a dispute resolution route if things go wrong.
      RECC Renewable Energy Consumer Code. Covers contract terms, cancellation rights, deposit protection and complaints handling.
      NAPIT Electrical competence and Part P compliance for the electrical work.
      IWA Deposit and guarantee protection — relevant if a company fails between your payment and your installation.
      Tesla Certified / GivEnergy Approved / Fox Elite Manufacturer-level training on specific battery and inverter systems. Matters most for warranty claims on those brands.
      TSI approved code Trading Standards approved code of practice.
      Octopus trusted partner A commercial partnership, not a quality accreditation. They offer a free tariff review and there is a £50 switching credit involved. Useful, but read it as a partnership rather than an endorsement of installation quality.

      MCS, TrustMark and RECC all publish searchable public registers. It takes about two minutes to check a company on each. Do that for every installer you shortlist — including this one. A logo on a website is a claim; a register entry is evidence.

      The warranty and finance small print

      Two warranties, and one of them is short

      Blue Ape lists panel performance cover of up to 25–30 years and inverter and battery warranties of roughly 10–12 years. Those are manufacturer warranties and broadly in line with the market.

      The installation itself carries a two-year insurance-backed workmanship warranty.

      Two points about that. The good part is “insurance-backed” — it is underwritten by a third party, so the cover survives even if the company does not. That is genuinely better than an uninsured promise, and not universal in this trade.

      The less good part is the duration. Two years is on the short side for workmanship cover; several installers offer five or ten. Roof penetrations that will leak usually leak in the first year or two, so two years is not unreasonable — but it is a fair question to put to them directly, and worth asking whether an extension is available and at what cost.

      The finance options are not equivalent

      Blue Ape offers two finance routes through Ideal4Finance. BlueApe Limited is an introducer appointed representative of Ideal Sales Solutions Ltd trading as Ideal4Finance, which is a credit broker rather than a lender, FRN 703401. The difference between the two options is substantial.

      Based on the representative examples published for a £5,150 system with a £200 deposit, giving a £4,950 loan.
      0% APRBuy now, pay later
      Term24 months6 months interest-free, then 60 months
      Rate0.00% APR fixed14.90% APR fixed
      Monthly payment£206.25£117.50
      Total repaid£4,950.00£7,050.03
      Cost of borrowing£0£2,100
      Read that table carefully. The lower monthly payment costs an extra £2,100 over the term — more than 40% on top of the system price. On our earlier payback numbers, an entry system saving around £391 a year would take roughly 13 years to repay at 0%; on the deferred option, the borrowing cost alone consumes more than five years of savings. If you can afford £206 a month, the 0% option is dramatically better value. Both are subject to status, and lending decisions sit with the lender, not the installer.

      Pros and cons

      What we rate

      • Published pricing. Rare in this industry, and it removes the salesperson-markup problem entirely.
      • £200 fully refundable deposit that locks pricing while the survey happens.
      • A published “not included” list. Scaffolding beyond one elevation, consumer unit upgrades, asbestos, roof repairs and more are stated upfront rather than appearing as variations later.
      • Accreditation depth, including all the ones that actually matter (MCS, TrustMark, RECC, NAPIT) and all independently checkable.
      • Insurance-backed workmanship warranty.
      • They repair third-party systems, which suggests real diagnostic capability rather than fit-and-forget.
      • Shading handled properly — they specify micro-inverters or optimisers where needed rather than ignoring the issue.
      • A public review from a customer they talked out of a battery. Worth something.

      What to question

      • The headline price is a small system. 2.73kWp at £1,886/kWp is above the national average per kWp, and most homes need more than six panels.
      • No published price above the entry tiers. Anything 4kW and up is a custom quote, which is where most buyers land.
      • Two-year workmanship warranty is shorter than some competitors offer.
      • The 3.2kWh entry battery is small and, on flat-tariff solar storage alone, hard to justify on payback arithmetic.
      • The deferred finance option is expensive — £2,100 in interest on a £4,950 loan.
      • 70-plus Trustpilot reviews is a good rating on a modest sample compared with national operators.
      • Southport-based but covering three nations. Fine for installation; worth asking what response times look like for aftercare if you are several hours away.

      Questions to ask them specifically

      If you do request a quote, these are the ones that will tell you most:

      1. What is the predicted annual output in kWh for the system you are proposing on my roof, allowing for its orientation and any shading?
      2. What is the price per kWp at the system size I actually need, not the entry package?
      3. Is the two-year workmanship warranty extendable, and what would that cost?
      4. Which inverter exactly — and is it a hybrid, so I can add storage later without replacing it?
      5. What self-consumption percentage is your battery savings figure based on, and which export tariff?
      6. Does my roof need any work first, and is that inside or outside the quoted price?
      7. Who handles the SEG registration, and will I receive the MCS certificate documentation I need to apply?
      8. If something fails in year three, who attends, how quickly, and is there a call-out charge?

      Ask the same eight questions of every installer you speak to. The answers, side by side, will tell you more than any review will — including this one.

      How they compare on the things that matter

      Our assessment against the criteria we think matter most when choosing an installer.
      Price transparencyExcellent — among the few UK installers publishing a real price list
      AccreditationExcellent — comprehensive and independently verifiable
      Value per kWpFair — competitive once you scale up, above average at entry size
      WarrantyGood on products, average on workmanship duration
      FinanceGood if you take the 0% option; poor value on the deferred route
      AftercareStrong — dedicated repairs function, including third-party systems
      Sales approachReviews consistently describe no pressure, which matches the fixed-price model

      Should you use them?

      Blue Ape Renewables looks like a competent, properly accredited installer with a business model built around not haggling. If you find sales visits exhausting and want to know the number before anyone comes to your house, that model is worth real money in avoided hassle.

      They are not automatically the cheapest, and the published entry price is for a smaller system than most households should be buying. Neither of those is a mark against them; it is just a reason to treat the price list as a starting point rather than a final answer.

      Our recommendation is the same one we would give about any installer, including ones we have no arrangement with: get three quotes. Compare them on predicted annual generation, named equipment, total specification and warranty terms. If Blue Ape comes out competitive on those, the transparency and the accreditation depth are genuine reasons to prefer them. If they do not, you have lost nothing but an afternoon.

      Get a quote and compare it

      Free, no-obligation, and the £200 deposit that holds your price is refunded in full if you walk away.

      Request your free quote →

      Affiliate link — we may earn a commission if you buy. Read our full UK solar panel guide first for current costs, export tariff rates and grant deadlines, so you can judge any quote you receive on the numbers.

      Frequently asked questions

      Is Blue Ape Renewables MCS certified?

      Yes. They list MCS certification alongside NAPIT, RECC, TrustMark, EVCC, IWA and a TSI-approved code. MCS is the one that determines your Smart Export Guarantee eligibility, so it is worth verifying on the MCS public register before you sign anything — a two-minute check that applies to any installer, not just this one.

      How much does a Blue Ape solar system cost?

      Published prices start at £5,150 for a 2.73kWp six-panel system, or £6,615 with a 3.2kWh battery. Standalone battery storage starts at £1,465. Larger systems fall into a custom quote tier with no published price. Prices include 0% VAT, which applies to residential solar until 31 March 2027.

      Is the £200 deposit refundable?

      Yes. It secures current pricing while the technical survey is carried out, and is refunded in full if you decide not to proceed, or if the survey finds your property unsuitable.

      Where do Blue Ape Renewables operate?

      They are based in Southport and install across England, Scotland and Wales. If you are a long way from the north west, it is worth asking specifically about aftercare response times rather than just installation availability.

      Do they install Tesla Powerwall?

      Yes — they are Tesla Certified for Powerwall installation, and also approved for GivEnergy and Fox ESS systems. Manufacturer certification matters mainly for warranty claims on those specific products.

      What is included in the installation price?

      Panels, inverter, mounting, wiring, MCS registration, DNO notification, monitoring setup, commissioning, a bird deterrent on systems under 12 panels, and one elevation of scaffolding up to 8m. Excluded unless quoted: additional scaffolding, roof repairs, asbestos removal, consumer unit upgrades, ground-mount frames, three-phase upgrades and removal of existing panels.

      Is the 0% finance genuinely 0%?

      The 24-month option is genuinely 0.00% APR — you repay exactly what you borrow. The alternative deferred option is 6 months interest-free followed by 60 months at 14.90% APR, which on the published representative example turns a £4,950 loan into £7,050 repaid. Both are subject to status, and lending decisions are made by the lender.

      Do they service systems installed by other companies?

      Yes. They run a repairs and service function covering inverter faults, health checks, EICR inspections and relocating equipment from loft spaces, on systems they did not install.


      Sources and method

      Pricing, package specifications, inclusions, exclusions, warranty terms, accreditations and finance representative examples taken from Blue Ape Renewables’ published website material, September 2026. Electricity unit rate of 26.32p/kWh from Ofgem’s price cap for 1 October to 31 December 2026. National average installed cost of approximately £1,785 per kW from government MCS installation data, June 2026. Payback calculations are our own, using stated assumptions, and are illustrative rather than a projection for any specific property.

      We have deliberately not applied review or star-rating structured data to this page, because we have an affiliate relationship with the company reviewed and self-serving review markup is against Google’s guidelines. Our assessment is stated in plain text above so you can weigh it yourself.

      This article is general information, not financial advice. Prices, tariffs and scheme rules change frequently — confirm current figures directly with the company before making a decision.

    • Solar Panel Cost UK 2026: Real Prices, Payback and Export Rates

      Last updated: September 2026  |  Reading time: about 12 minutes

      Affiliate disclosure: This guide contains affiliate links. If you request a quote through one of them and go on to buy, we may earn a commission at no extra cost to you. It does not change the price you pay, and it does not change what we write. Every figure below is sourced and dated so you can check it yourself.

      Here is the short version: a 4kW solar system costs roughly £5,500 to £8,500 installed in 2026, generates around 3,400 kWh a year in most of England, and pays for itself in roughly 9 to 13 years depending on where you live, how much electricity you use during daylight hours, and which export tariff you sign up to.

      That last factor matters far more than most people realise. Two identical systems on two identical roofs can differ by over £200 a year in income purely because of which supplier pays for the exported electricity. We will come back to that.

      This guide gives you the actual numbers — installation costs by system size, a worked payback calculation you can adapt to your own bills, current export rates, which grants still exist and when they close, and the specific questions that separate a fair quote from an expensive one.

      Key figures at a glance

      • 4kW system: £5,500–£8,500 installed. Government MCS data put the average at about £1,785 per kW for 4–10kW systems as of June 2026, which works out at roughly £7,140 for 4kW.
      • Adding a battery: a further £3,000–£8,000. Complete solar-plus-battery packages typically land between £9,000 and £14,000.
      • VAT: 0% on residential solar and battery installations until 31 March 2027.
      • Electricity price: 26.32p per kWh under Ofgem’s price cap for 1 October to 31 December 2026, with a standing charge of 54.83p a day.
      • Export income (SEG): anywhere from about 3p to 25p per kWh depending on supplier and conditions.
      • ECO4 grant scheme: closes 31 December 2026. No ECO5 is planned.

      How much do solar panels actually cost in 2026?

      Solar has become meaningfully cheaper. Panel and inverter prices have fallen, and the zero VAT rating removes a fifth of the bill that homeowners were paying before April 2022.

      Here is what the market looks like right now for MCS-certified installations. These prices should include panels, inverter, mounting hardware, scaffolding, electrical work, DNO notification and commissioning.

      Typical installed prices, UK, 2026. London and the South East generally sit at the upper end. Prices include 0% VAT.
      System size Panels (approx.) Roof space needed Typical annual output Installed cost
      3kW 7–9 11–16 m² ~2,550 kWh £5,000–£6,500
      4kW (most common) 8–14 13–22 m² ~3,400 kWh £5,500–£8,500
      6kW 13–18 22–32 m² ~5,100 kWh £8,500–£11,000
      4kW + 5kWh battery 8–14 13–22 m² ~3,400 kWh £9,000–£12,000
      8kW + battery 18–24 30–42 m² ~6,800 kWh £13,500–£17,500

      Why quotes for the same system vary by thousands

      A 4kW system is not one product. The spread between a £5,500 quote and an £8,500 quote usually comes down to specific, checkable things:

      • Panel tier. Established manufacturers such as Trina, JA Solar, Longi or REC typically carry 25-year linear performance warranties. Budget panels can save £300–£650 up front but often come with 10–15 year cover.
      • Inverter type. A basic string inverter is cheapest. A hybrid inverter (battery-ready) costs more but saves you replacing it later. Micro-inverters or optimisers cost more again, and are genuinely worth it if any part of your roof is shaded.
      • Roof complexity. A simple south-facing pitched roof is quick. Multiple orientations, slate, a three-storey terrace or awkward scaffolding access all add cost.
      • Scaffolding. Usually £750–£1,800, and it should be itemised. If your quote does not mention it, ask whether it is included.
      • Battery size and brand. The single biggest variable. A 5kWh unit and a 13.5kWh Tesla Powerwall are not comparable line items.
      A useful timing tip: installer pricing tends to soften in the quieter months. Fitting teams are busiest from spring through late summer, so quotes taken between September and February often come in lower. If your roof covering is over 30 years old, doing solar at the same time as a re-roof saves a second scaffolding hire.

      What will you actually save? A worked example

      This is where most solar articles go vague. So let us do the arithmetic properly, using figures you can swap for your own.

      Our assumptions: a 4kW system in the Midlands costing £7,000, generating 3,400 kWh a year. Electricity bought from the grid at 26.32p per kWh (Ofgem’s cap rate for the final quarter of 2026). Export paid at 12p per kWh, which is a realistic mainstream rate rather than a headline one.

      The critical number is self-consumption — the share of what your panels generate that you actually use yourself, rather than exporting. Every kWh you use yourself is worth 26.32p to you. Every kWh you export is worth 12p. The gap is more than double.

      Illustrative annual returns for a 4kW system. Your figures will differ; the method is what matters.
      Solar only Solar + 5kWh battery
      Installed cost £7,000 £11,000
      Annual generation 3,400 kWh 3,400 kWh
      Self-consumption rate 35% 70%
      Electricity you avoid buying 1,190 kWh = £313 2,380 kWh = £626
      Electricity exported 2,210 kWh = £265 1,020 kWh = £122
      Total annual benefit £578 £748
      Simple payback ~12 years ~15 years

      Look carefully at that last row, because it is the opposite of what most solar advertising implies.

      The battery increases your annual saving but lengthens your payback. It adds £170 a year in this example, and costs £4,000. That is a 23-year return on the battery alone, against a typical 10-year manufacturer warranty.

      This is not an argument against batteries. It is an argument against buying one without doing this specific calculation for your own household. A battery earns its keep when it is doing more than storing surplus solar — for instance charging overnight on a cheap off-peak tariff and discharging during the expensive evening peak, or exporting into a high time-of-use rate. On a standard flat tariff, storing solar alone, the numbers are much harder to justify.

      Watch out for this in sales conversations: if a quote shows the battery paying for itself in five or six years, ask exactly which tariff and which self-consumption percentage the figure assumes. The assumptions are where optimistic projections live.

      How your roof changes everything

      Orientation and shading affect output more than panel brand does. As a rough guide, relative to a perfect south-facing pitched roof:

      Approximate annual output relative to due south at 30–40° pitch. Indicative only — an installer’s site survey uses your actual roof geometry.
      Orientation Approx. output Verdict
      Due south 100% Ideal
      South-east / south-west ~95% Barely any loss
      East / west ~80% Still viable, and spreads generation across morning and evening
      North-east / north-west ~65% Marginal
      Due north ~60% Rarely worth it

      An east-west split is not the disaster it sounds. It produces less in total, but it produces earlier and later in the day, which can push your self-consumption rate higher than a south-facing array that peaks at noon when nobody is home.

      Shading is the bigger threat. A single chimney, aerial or neighbouring tree shading part of one panel can drag down a whole string of panels on a basic string inverter. If you have any shading, ask specifically about power optimisers or micro-inverters.

      Seasonality is worth bracing for too: roughly 70% of a UK system’s annual generation arrives between April and September. December output can be under a tenth of June’s. That is normal, not a fault.

      The Smart Export Guarantee: the part most people get wrong

      The Smart Export Guarantee (SEG) replaced the old Feed-in Tariff in January 2020. Under it, every licensed electricity supplier with 150,000 or more customers must offer at least one tariff paying you for electricity you export to the grid. Smaller suppliers can opt in voluntarily.

      The crucial difference from the old Feed-in Tariff: there is no government-set rate. Suppliers decide their own, and the only rule is that it must be above zero. Which is why the spread is enormous.

      What the rates look like

      Rates as reported through mid-2026 fell into three broad bands:

      Indicative SEG bands during 2026. Suppliers can change rates with notice — always confirm the current figure on the supplier’s own site before signing up.
      Band Typical rate The catch
      Top tier 17.5p–25p per kWh Usually requires that the supplier installed your system, and that you buy your electricity from them. Often fixed for 12 months.
      Bundled mainstream 12p–16.5p per kWh Requires you to take your import supply from the same company.
      Standalone 3p–6p per kWh No switching required — and it shows in the rate.
      Time-of-use Up to 30p+ at peak Needs a battery and a smart meter. You are paid the high rate only for exports during the evening peak window, typically 4–7pm.

      Reporting through 2026 pointed to Good Energy at the top of the fixed-rate market at around 25p for its own installations, with So Energy and OVO around 20p, EDF around 18p and E.ON Next around 16.5–17.5p. British Gas sat near 15p. Octopus cut its Outgoing tariff from 15p to 12p on 1 March 2026, which removed what had been many people’s default choice.

      Do the arithmetic on that spread. Exporting 2,200 kWh a year at 15p earns £330. The same electricity at 4p earns £88. Same panels, same roof, same sunshine — a £242 annual difference from a form you fill in once.

      Two things almost nobody realises:
      1. Your export supplier does not have to be your electricity supplier. You can buy power from one company and be paid for exports by another — though, as the table shows, most of the better rates are conditional on bundling.
      2. SEG payments are not automatic. Installing panels does not enrol you. You have to apply directly to a supplier. Electricity you export before you sign up earns you nothing.

      What you need to qualify

      • An eligible low-carbon system — solar PV, wind, hydro, anaerobic digestion or micro-CHP — within the capacity limits.
      • MCS certification (or an accepted equivalent) for both the installation and the installer. Suppliers routinely ask to see the certificate.
      • A meter capable of half-hourly export readings — in practice, a smart meter — plus an export MPAN. That is a different number from the import MPAN on your bill; your export supplier normally arranges it.
      • The property must be in Great Britain. SEG is not available in Northern Ireland.

      This is the practical reason MCS certification matters so much. It is not a badge. Without it, most suppliers will not put you on a SEG tariff at all, which quietly removes a chunk of your return for the next 25 years.

      The scheme is not a niche curiosity, either. Ofgem reported 270,395 registered installations by the end of SEG Year 5, with around £57 million paid out for 443 GWh of exported electricity across that year.

      Grants in 2026: what is real and what is not

      “Free solar panels” advertising is relentless, and mostly misleading. Here is the honest position as of September 2026.

      0% VAT — open to everyone

      Solar panels, batteries and their installation are zero-rated for VAT on residential properties. This is the one incentive that applies regardless of income, benefits or EPC rating. It is worth roughly £1,000–£2,000 on a typical installation, and the current zero rating runs until 31 March 2027.

      ECO4 — closing 31 December 2026

      The Energy Company Obligation is the scheme that can genuinely fund solar in full, but it is not a cash grant. It is an obligation on large energy suppliers to fund efficiency upgrades for eligible households, delivered through approved installers.

      Broad eligibility: your property has an EPC rating of D, E, F or G, and someone in the household receives a means-tested benefit such as Universal Credit, Pension Credit, Housing Benefit, income-based JSA or ESA, or Income Support. Some councils also refer households through “LA Flex”, which uses local fuel-poverty criteria rather than benefits — worth asking your council about if you are on a low income but not on benefits.

      The important caveat: ECO4 is a whole-home retrofit scheme, not a solar scheme. It leads with insulation and heating, because in a cold, inefficient home those do more good. Solar can be included where the property assessment supports it, but standalone solar is rarely funded.

      The government confirmed a nine-month extension in January 2026, moving the close from 31 March to 31 December 2026. There will be no ECO5. Applications take time to process and installer capacity tightens as any scheme approaches its deadline, so if you think you qualify, this is genuinely a case for acting rather than waiting.

      The Great British Insulation Scheme — closed

      GBIS ended on 31 March 2026 and has not been directly replaced.

      The Warm Homes Plan — from January 2027

      This is the successor, and it is a structural change rather than a rebrand. Instead of obliging energy suppliers to fund upgrades (a cost that ultimately sits on everyone’s bills), the Warm Homes Plan is funded by direct government spending, with a headline commitment in the £13–15 billion range across this parliament and a target of upgrading five million homes by 2030. Rooftop solar is explicitly in scope.

      Two elements are relevant to solar buyers: fully funded packages for low-income households through the Warm Homes: Local Grant, delivered by local councils; and a low-interest or interest-free loan scheme intended to be open to all households. Detailed eligibility and loan terms were still being finalised through 2026.

      Grant scam red flags. Be sceptical of anyone who: promises free solar without naming a specific scheme; contacts you cold by phone or doorstep; claims a government grant is “about to expire” and pressures you to sign today; asks for an upfront fee to “check eligibility”; or will not provide an itemised written quote. Genuine scheme funding is delivered through approved installers, and checking whether you qualify never costs money.

      How to read a solar quote properly

      Get three quotes. Not one. The spread on identical specifications is routinely large enough to fund a battery.

      When comparing them, the headline price tells you almost nothing on its own. These are the line items that matter:

      1. Exact equipment, named

      A quote that says “solar system” or “10 panels” is not a quote. You want the panel manufacturer and model, the wattage per panel, the inverter make and model, and if a battery is included, its brand and usable capacity in kWh. Usable capacity, not nominal — they are not always the same number.

      2. Predicted annual generation in kWh

      Not the number of panels. Ask for the estimated annual output in kilowatt-hours, and ask whether the figure accounts for your roof’s actual orientation and any shading. An MCS-certified installer produces this as standard.

      3. What is included in the price

      Scaffolding, electrical work, DNO notification, bird protection mesh, DC isolators, monitoring hardware, MCS certificate, and making good afterwards. Ask directly whether anything is excluded.

      4. Two separate warranties

      There is the product warranty from the manufacturer, and the workmanship warranty from the installer. The second is the one people forget. If a roof penetration leaks in year four, the panel manufacturer is not the one fixing your ceiling. Ask how long the workmanship cover runs and whether it is insurance-backed, meaning it survives the installer going out of business.

      5. Grid connection paperwork

      Systems with an inverter rated at 3.68kW or below fall under G98 and can be connected with notification to your Distribution Network Operator afterwards. Larger systems need G99 approval before installation, which takes time. Confirm which applies and who is handling it.

      6. Certification you can verify

      MCS certification is the one that determines your SEG eligibility. RECC and TrustMark provide consumer protection and dispute resolution. NAPIT or NICEIC covers electrical competence. Verify these on the certifying bodies’ own registers rather than trusting logos on a website. MCS, TrustMark and RECC all publish searchable databases.

      7. Deposit protection

      If you are asked for a deposit, ask how it is protected. Deposit and guarantee insurance exists precisely because installers occasionally fail between payment and installation.

      Who solar genuinely suits — and who it does not

      Strong case: you own your home and plan to stay 10+ years; you have an unshaded south, east or west-facing roof; someone is home during the day, or you can shift laundry, dishwashing and hot water to daylight hours; you have an EV or heat pump, or expect one; your electricity use is above average.

      Weaker case: you may move within five years; your roof is heavily shaded or predominantly north-facing; your household is out all day and on a flat tariff with no battery; your roof covering needs replacing soon (do the roof first); you are in Northern Ireland, where SEG does not operate and the export picture is different.

      None of these are absolute. A household that is out all day but adds a battery and a time-of-use tariff can do perfectly well. The point is that the answer is specific to your home and your habits, which is why a generic online calculator is a starting point rather than a conclusion.

      Getting quotes

      If you want a personalised assessment, Blue Ape Renewables is one MCS-certified installer offering free, no-obligation quotes for solar PV, battery storage, heat pumps and EV charging. They list MCS, NAPIT, RECC, TrustMark and Tesla Certified accreditations, and install Tesla Powerwall, GivEnergy and Fox ESS systems.

      Get a free solar & battery quote →

      This is an affiliate link — we may earn a commission if you buy. We would give you the same advice either way: get at least three quotes and compare them line by line using the checklist above. One quote is not a comparison, whoever it comes from.

      Frequently asked questions

      How long do solar panels last?

      Panels typically carry 25-year performance warranties, with output degrading gradually — usually guaranteed to remain above roughly 80–85% of original capacity at year 25. They generally keep working beyond that, just less efficiently. Inverters are the shorter-lived component, often needing replacement at 10–15 years. Budget £800–£1,500 for that when assessing lifetime returns.

      Do solar panels work on cloudy days?

      Yes, but at reduced output. Panels respond to daylight rather than direct sunshine, so they generate on overcast days at a fraction of peak capacity. This is why UK annual output figures already account for the weather — 3,400 kWh from a 4kW system is a real-world British number, not a Mediterranean one.

      Do I need planning permission?

      For most homes, no. Roof-mounted solar on a domestic property usually falls under permitted development in England, Scotland and Wales. The main exceptions are listed buildings, homes in conservation areas or National Parks, and flat-roof or ground-mounted installations. Check with your local planning authority if any of those apply.

      Will solar panels increase my home’s value?

      Evidence points to a modest positive effect, mainly through the improved EPC rating and the appeal of lower running costs. But treat it as a secondary benefit rather than a reason to install. Buyers value an owned system considerably more than one under a lease or rent-a-roof arrangement, which can complicate a sale.

      Should I get a battery at the same time or add one later?

      Retrofitting is possible but usually costs more than doing it together, because you may need to replace or supplement the inverter. If a battery is a realistic possibility within a few years, ask for a hybrid (battery-ready) inverter at the outset. It costs a little more now and avoids a much larger bill later.

      What happens to my panels during a power cut?

      By default, nothing — the system shuts down for safety, so grid engineers are not working on live wires. Your panels will not power your home during an outage unless you have a battery with a dedicated backup function and the correct gateway hardware. If blackout resilience matters to you, say so explicitly at quotation stage, because it is not standard.

      Do I pay tax on SEG income?

      HMRC provides a £1,000 annual trading allowance, and typical household export earnings fall comfortably below it. If your circumstances are unusual, check with HMRC or an accountant — we are not tax advisers.

      Can I get SEG payments if I already have Feed-in Tariff?

      The Feed-in Tariff closed to new applicants in 2019, but existing participants continue under their original agreements, which are generally more generous than SEG. Switching schemes is rarely worthwhile. If you are on FiT, check your export terms before changing anything.

      Are solar panels worth it in Scotland?

      Yes, though payback is longer. Scottish output typically runs 10–15% below southern England, pushing typical payback towards 11–14 years rather than 7–9. Scotland also has its own support schemes separate from ECO4 and the Warm Homes Local Grant, so check devolved options.

      The verdict

      Solar panels are worth it for a large number of UK households in 2026 — but for reasons more specific than the advertising suggests.

      The economics work best when three things line up: a decent roof, a household that can use a good share of what it generates during daylight hours, and a competitive export tariff. Get those right and a 4kW system returning £500–£600 a year against a £7,000 outlay is a solid, low-risk return on capital, especially with electricity at 26p a unit and the price cap forecast to rise again in early 2027.

      Where people lose money is in the details: overpaying by £2,000 because they took the first quote; adding a £4,000 battery that saves £170 a year on the wrong tariff; or never signing up to SEG at all and giving away 2,000 kWh a year for free.

      So the practical sequence is: work out your annual electricity consumption from your bills, get three itemised quotes from MCS-certified installers, compare them on predicted kWh and total specification rather than headline price, and choose your export tariff deliberately rather than accepting whatever your installer suggests.

      Do that, and you will know whether solar is worth it for your house — which is the only version of the question that has a real answer.


      Sources and dates

      Installation costs: MCS installation data and market surveys, 2026. Electricity unit rate and price cap: Ofgem, price cap for 1 October to 31 December 2026 (announced 26 August 2026). SEG rules and eligibility: Ofgem and Energy Saving Trust. SEG rate bands: supplier tariff comparisons published between May and August 2026. ECO4 extension: government consultation response, 23 January 2026. Warm Homes Plan: GOV.UK, January 2026. VAT: zero rating on residential energy-saving materials to 31 March 2027.

      This article is general information, not financial advice. Energy tariffs, grant schemes and prices change frequently — verify current figures with the relevant supplier or scheme before making a decision.

    • How to Build Money Habits That Actually Stick (Without the Stress)

      Most money advice fails for a simple reason: it asks you to rely on willpower. Track every penny. Never impulse buy. Say no to every takeaway. This works for about two weeks, and then real life gets in the way and the whole system collapses — often followed by guilt, which makes the next attempt even harder to start.

      The households that manage money well long-term aren’t more disciplined than everyone else. They’ve just built a small number of habits that don’t require daily willpower to maintain. This guide covers what those habits actually look like, and how to build them without the stress that usually derails good intentions.

      Why Willpower-Based Budgeting Fails

      Willpower is a limited resource that runs lowest exactly when you need it most — after a long day, when you’re tired, stressed, or in a shop surrounded by deliberately designed temptation. Relying on “just not buying it” as your main strategy means your budget is only as strong as your worst moment of the week.

      Systems don’t have this problem. A system that automatically moves money into savings the day you’re paid doesn’t care how tired you are. A rule that says “wait 24 hours before any purchase over £50” doesn’t require you to feel strong in the moment — it just requires you to have set the rule in advance.

      The Habits Worth Building First

      Not all money habits are equally valuable. A handful account for most of the difference between households that save consistently and those that don’t.

      1. Automate before you can spend it

      Set up a standing order that moves a fixed amount to savings on payday, before it reaches your everyday spending account. This removes the decision entirely — you’re not choosing to save each month, you already have.

      2. Use a cooling-off rule for non-essentials

      A simple 24-hour rule for anything over a set threshold (£30, £50 — whatever fits your budget) filters out most impulse purchases without banning spending outright. Most impulse urges fade within a day; the ones that don’t were probably worth buying anyway.

      3. Review recurring payments quarterly, not never

      Subscriptions and recurring charges are the single biggest source of quiet financial leakage, because they’re designed to be forgotten. A ten-minute review every three months — cancelling what you no longer use — tends to save more over a year than any single discount code or cashback offer.

      4. Compare before trusting a “deal”

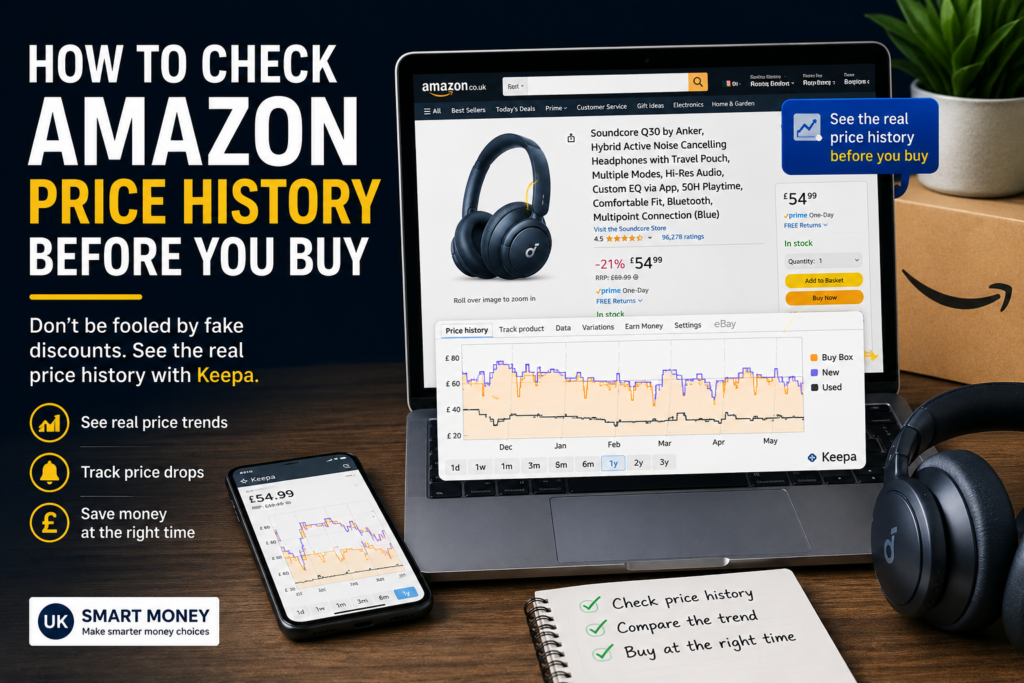
      A discount is only real relative to a fair starting price. Before treating any offer as a saving, a quick check of whether the price has genuinely dropped (rather than just being marked as reduced) prevents the most common way “deals” quietly cost money instead of saving it.

      5. Separate “spending money” from “everything else”

      Keeping a portion of your income in a separate account purely for discretionary spending — takeaways, hobbies, shopping — means you can spend freely within that pot without needing to mentally calculate the impact on rent or bills every time. This removes decision fatigue and the stress of constantly checking a single combined balance.

      What to Do When You Slip Up

      Every system has weeks where it doesn’t work — an unexpected cost, a bad week, a moment of stress-spending. The difference between people who stay on track long-term and people who abandon the whole approach isn’t that the first group never slips. It’s that they don’t treat one bad week as proof the system has failed.

      Practically, this means: if you overspend one month, you simply return to the automated habits the next month, rather than trying to “make up for it” with extreme restriction that’s unlikely to last. Consistency over months matters far more than perfection in any single week.

      Small Decisions, Compounded

      None of the habits above require spreadsheets, budgeting apps, or hours of admin. They require setting up a handful of defaults once, and then largely getting out of your own way. That’s a deliberately low-effort approach — not because effort is bad, but because habits that require constant effort are the ones that quietly stop happening after a few weeks.

      The goal isn’t to become a different kind of person who finds saving effortless. It’s to build a small number of systems that make good decisions automatic, so the actual willpower you have left is spent on things that matter more than resisting a checkout page.


      Want the shopping-specific side of saving money? See our complete guide to saving money online in the UK for how to combine these habits with discount codes and cashback.

    • The Ultimate Guide to Cashback in the UK

      How It Works and How to Maximise It

      Cashback sounds almost too simple: you shop as normal, and a percentage of what you spend comes back to you. But most people either don’t use it at all, or use it badly — chasing rates instead of building a system. This guide explains exactly how cashback works behind the scenes, what actually earns you the most over a year, and where people lose money without realising it.

      How Cashback Actually Works

      When you click through a cashback platform to a retailer’s website, a tracking cookie or affiliate link records that the visit came from that platform. If you complete a purchase, the retailer pays the platform a commission for referring you — and the platform shares a portion of that commission back with you as cashback.

      This is why cashback is free to you: the retailer is already paying for the referral either way. You’re simply capturing part of a marketing budget that would otherwise go entirely to a middleman.

      The steps that determine whether it works:

      1. You start your shopping session by clicking through the cashback platform, not by searching the retailer directly
      2. You complete the purchase in the same browsing session, ideally without closing tabs or switching devices
      3. The retailer confirms the sale after any return period has passed
      4. The cashback platform pays out, usually with a delay of several weeks

      Skipping step one is the single most common reason cashback doesn’t track. If you open a new tab, search for the retailer directly, and buy from there, the platform has no way of knowing the visit came from you.

      Why Cashback Sometimes Doesn’t Track

      This is the part that frustrates people most, so it’s worth explaining clearly. Tracking can fail for reasons that have nothing to do with the platform being unreliable:

      • Ad blockers or strict cookie settings can block the tracking pixel entirely
      • Using an app instead of a browser sometimes bypasses tracking unless the platform has its own app integration
      • Applying a discount code found elsewhere can occasionally overwrite the affiliate tracking, depending on how the retailer’s checkout is built
      • Comparing prices in multiple tabs before buying can cause the “last click” to come from a different source

      The practical fix is simple: disable ad blockers for the retailer’s site during checkout, use one browser tab from click to purchase confirmation, and avoid switching devices mid-purchase.

      What Realistic Cashback Rates Look Like

      Cashback rates vary by category, and understanding the pattern helps you know what’s a genuinely good rate versus an average one:

      • Fashion and general retail: typically 2–8%, higher during promotional periods
      • Travel and holidays: often lower percentage but higher absolute value given the size of the purchase
      • Financial products and switching services (bank accounts, insurance, broadband): usually a fixed cash amount rather than a percentage, often the highest-value category per action
      • Everyday groceries and takeaways: usually low, single-digit percentages, but rewarding because of purchase frequency

      The biggest wins tend to come from switching services — bank accounts, energy, insurance — rather than shopping cashback, simply because those payouts are flat amounts that don’t require ongoing spending.

      Referral Bonuses vs Cashback: What’s the Difference

      Referral bonuses, common with fintech apps like digital banks and investment platforms, work on a different mechanism to shopping cashback. Instead of a percentage of a purchase, you get a fixed reward for successfully referring someone who signs up and meets a specific action — often opening an account and making a first deposit or transaction.

      A few things worth checking before relying on any referral bonus:

      • What exactly counts as a “successful” referral (signup alone is rarely enough)
      • Whether there’s a cap on how many referrals you can make
      • How long payout takes, and whether it’s paid as cash or as credit/points
      • Whether the person you refer also benefits, which affects how easy it is to convince them

      Referral schemes are generally low-risk for the referrer, since you’re not spending money to refer someone — you’re simply sharing a code. The main “cost” is the effort of asking, and the risk that the friend doesn’t complete the required action, meaning neither of you gets anything.

      Building a Simple Cashback System

      The people who benefit most from cashback aren’t the ones chasing the highest rate on every purchase — they’re the ones who’ve built a boring, repeatable habit:

      1. Pick one or two platforms and stick with them rather than spreading thin across five apps
      2. Install the browser extension if one exists, so you’re reminded automatically before checkout rather than relying on memory
      3. Check the rate at the moment of purchase, since rates fluctuate and a platform showing 5% last week might show 2% today
      4. Track pending vs confirmed cashback loosely — don’t count it as spent money until it’s actually paid out
      5. Combine with discount codes where allowed, but check the retailer’s terms first, since some exclude sale or discounted purchases from cashback tracking entirely

      The Bottom Line

      Cashback isn’t a way to save on things you weren’t already going to buy — treated that way, it becomes a reason to overspend rather than a reason to save. Treated correctly, as a small, consistent bonus layered on top of purchases and switches you were making anyway, it adds up meaningfully over a year without requiring extra effort once the habit is built.


      Looking for specific platforms? See our reviews of cashback apps and referral bonus programmes to find out which fits your shopping habits best.

    • The Complete Guide to Saving Money Online in the UK (2026)

      Online shopping has never been easier — or more expensive, if you’re not paying attention. Between subscription creep, “limited time” sales that run every week, and delivery fees that quietly double your basket total, it’s easy to overspend without noticing. The good news is that saving money online isn’t about being tight-fisted. It’s about knowing a handful of systems and using them consistently.

      This guide pulls together everything you need: how discount codes actually work, how cashback apps make money (and how you keep more of it), how to spot a fake deal before it costs you, and the habits that separate people who save hundreds a year from people who just mean to.

      Why Most People Overpay Online

      Retailers rely on a simple psychological pattern: urgency plus friction. A countdown timer creates urgency. A checkout process that doesn’t prompt you to look for a code creates friction — most shoppers simply forget to check. Studies on UK online shopping behaviour consistently show that a large share of shoppers abandon their basket specifically to search for a discount code, then either give up or forget to come back.

      The fix isn’t complicated: build the habit of checking two or three trusted sources before you open your wallet, every single time. That’s it. The rest of this guide is about doing that efficiently.

      Step 1: Discount Codes — Getting Them Right

      A discount code (or voucher code) is a string of letters and numbers that unlocks a specific offer at checkout — a percentage off, free delivery, or money off above a minimum spend. They’re usually issued directly by the retailer for marketing purposes, which means they’re free to use and carry no risk to you as a shopper.

      Where to actually find working codes:

      • The retailer’s own newsletter (often the freshest codes, since they’re first-party)
      • Established voucher code sites that list expiry dates clearly
      • Browser extensions that auto-apply codes at checkout, so you don’t have to hunt manually
      • Student or NHS discount schemes if you’re eligible — these often stack with general offers

      Common mistakes that waste people’s time:

      • Using codes from unverified social media posts, which are frequently expired or fake
      • Not checking the minimum spend requirement before adding items to match it
      • Forgetting that codes are usually single-use per account, not per order
      • Missing that some codes exclude sale items entirely

      If you want a deeper breakdown of how to tell a genuine code from a fake one, see our dedicated guide on spotting fake discount codes.

      Step 2: Cashback — Getting Paid to Shop You Were Already Doing

      Cashback works differently from a discount code. Instead of reducing the price at checkout, a cashback platform tracks your purchase through an affiliate link and pays you back a percentage afterwards — usually a few weeks later, once the retailer confirms the sale wasn’t returned.

      This matters because it changes your strategy: cashback is best for purchases you were already planning to make, not an excuse to buy more. The golden rule is simple — never buy something because there’s cashback on it. Buy it because you need it, and treat the cashback as a bonus.

      A few things worth knowing before you rely on cashback:

      • Tracking can fail if you use an ad blocker or have cookies disabled — always check the retailer page loaded correctly before buying
      • Rates change frequently, sometimes daily, so check the rate at the moment of purchase, not from memory
      • Payouts are rarely instant. Most platforms hold cashback as “pending” for 30–90 days before it’s confirmed and payable
      • Combining a discount code with cashback usually works, but not always — some retailers exclude sale-price purchases from cashback tracking

      Step 3: Comparing Before You Buy

      This is the step most people skip, and it’s the one that saves the most money. A 20% discount code on an overpriced item is still a bad deal. Before applying any code, take thirty seconds to check the price elsewhere — a quick search, a price history tool, or comparing two or three retailers directly.

      A simple three-question check before any purchase over £30:

      1. Has this item been cheaper recently? (Price history tools can show this in seconds)
      2. Is a competitor selling the identical item for less right now?
      3. Am I buying this because I need it, or because the deal makes it feel urgent?

      If the answer to the third question is “the deal,” it’s worth sitting on the purchase for 24 hours. Genuine good deals are rarely gone in a day; manufactured urgency almost always is.

      Step 4: Building the Habit Without the Stress

      Saving money online shouldn’t feel like a second job. The households that save the most consistently tend to do three simple things, not twenty complicated ones:

      • Keep one place for codes and cashback rates — a bookmarked folder or browser extension, rather than searching fresh every time
      • Set a personal rule for “cooling off” on non-essential purchases — even 24 hours reduces impulse spending significantly
      • Review subscriptions and recurring payments every few months — this tends to save more than any single discount code ever will, because it stops ongoing leakage rather than one-off spend

      None of this requires spreadsheets or extreme budgeting. It requires consistency more than intensity.

      Putting It Together

      Here’s the realistic version of “saving money online” that actually works long-term:

      1. Never check out without spending thirty seconds looking for a valid code
      2. Use cashback on purchases you’d make anyway, and treat it as a bonus, not a reason to buy
      3. Compare prices before trusting any “discount,” since the discount is only real relative to a fair starting price
      4. Build small, repeatable habits rather than relying on willpower during sales events

      None of these steps take long individually, but together they add up to hundreds of pounds a year for the average UK household — without changing what you buy, only how carefully you buy it.


      Looking for savings on a specific retailer? Browse our up-to-date discount code and voucher guides, or check out our cashback and fintech app reviews for ways to earn while you spend.

    • How to Check Amazon Price History Before You Buy

      Is That Amazon Deal Really a Deal? You see it all the time on Amazon. Was £79.99 — Now £49.99 — Save 38%. It looks like a bargain. But there is one problem: you don’t know whether £49.99 is actually a good price. The “was” price doesn’t tell you what the product normally sells for. A product might have been £49.99 for weeks before being advertised as a special deal. So before you click Buy Now, there is a simple question worth asking: What has this product actually cost over the last few months? That’s where an Amazon price history tracker such as Keepa becomes extremely useful. An Amazon deal may look impressive at first glance, but checking the price history can reveal whether you’re actually getting a good deal. What Is Amazon Price History? Amazon prices can change frequently. A product might be: – £59.99 on Monday – £54.99 on Wednesday – £44.99 during a promotion – £59.99 again the following week Looking only at today’s price doesn’t tell you whether £44.99 is a genuine bargain. A price-history chart lets you look backwards and see how the price has changed over time. This gives you something much more useful than a large red discount percentage: context. The Easiest Way to Check an Amazon Product’s Price History One of the best-known tools for this is Keepa. Keepa provides Amazon price-history charts and price-drop alerts, and its browser extension can display price-history information directly on supported Amazon product pages. Step 1: Find the Product on Amazon Go to Amazon UK and find the product you are considering. Don’t buy it yet. Copy the product’s Amazon page URL or use the Keepa extension if you have it installed. Step 2: Open the Price History With Keepa, you can view the product’s historical pricing information. Instead of seeing only today’s price, you can see how the price has moved over time. This is the part that can completely change your buying decision. Step 3: Look at the Bigger Picture Don’t just look at the lowest price. Look for patterns. Ask yourself: – Is today’s price close to the usual price? – Has the product been cheaper recently? – Does the price regularly fall during certain periods? – Is today’s “sale” price actually unusual? These questions are much more useful than simply looking at the percentage discount shown on Amazon. How to Read a Keepa Price Chart At first, a price-history graph can look complicated. You don’t need to understand every line. For a normal shopper, concentrate on three things. 1. Today’s Price Take the Anker Soundcore Q30 noise-cancelling headphones as an example. At the time of writing, the Keepa data shows a current Buy Box price of £54.99. That number by itself doesn’t tell you much. 2. The Normal Price Range Look at where the price has spent most of its time. For the Q30, Keepa shows an average price of £52.57 over the last 180 days and £55.82 over the last 365 days. At £54.99, the Q30 is therefore sitting very close to its typical selling price. In other words, it doesn’t appear to be an exceptional deal based on its recent price history. 3. The Historical Low Look for the lowest prices the product has reached. The Q30’s lowest price shown over the past year was £40.84, around eight months ago. That doesn’t mean you should wait forever for £40.84. But it does tell you something important: £54.99 is not close to the best price this product has reached. The important question is whether the current price is good compared with the product’s normal history, not whether it’s the lowest price it has ever been. Keepa price history for Anker Soundcore Q30 showing £54.99 current price, £52.57 180-day average and £40.84 one-year low. Keepa price history for the Anker Soundcore Q30, showing the current Buy Box price, 180-day average and one-year low. Keepa price history for Anker Soundcore Q30 showing £54.99 current price, £52.57 180-day average and £40.84 one-year low.” Example: A “£30 Saving” That Isn’t Really £30 Imagine Amazon shows: Was £79.99 Now £49.99 Save £30 That sounds impressive. But suppose the price history shows something like this: – £49.99 for most of January – £54.99 in February – £49.99 in March – £59.99 in April – £49.99 today Suddenly, the £30 saving doesn’t look quite as exciting. You’re not necessarily getting a bad price. You’re simply not getting the spectacular bargain the discount label might suggest. That’s why checking historical pricing is so useful. A Better Question to Ask Instead of asking: “How much money am I saving?” ask: “Is this one of the better prices this product has been sold for?” That’s a much better way to think about Amazon deals. The difference is subtle but important. A £20 discount isn’t automatically a good deal. A product costing £20 less than its previous price can still be poor value if the product itself isn’t worth £20. Check the Current Amazon Price If you’ve checked the price history and you’re happy with the deal, you can check the latest Amazon UK price before buying. “CHECK THE ANKER SOUNDCORE Q30 ON AMAZON UK” (https://amzn.to/4ql6VEV) Remember that Amazon prices can change at any time, so always check the current price on the product page before purchasing. Don’t Make This Mistake With Amazon Price History There is one important limitation: price history does not tell you whether a product is good. It only helps you understand the price. A product can be at its lowest historical price and still be a bad purchase. Before buying, you should also consider: – Customer reviews – Review quality rather than just the star rating – Product specifications – Seller reputation – Warranty – Return policy – Whether you actually need the product Price history should be one part of your decision, not the entire decision. Keepa Can Also Alert You When the Price Drops One of the most useful features of Keepa is price-drop tracking. Instead of repeatedly checking Amazon yourself, you can set up an alert for a product you’re interested in. For example, you might decide: “I’ll buy this if it drops below £40.” Rather than paying £49.99 today, you can wait and let the price tracker notify you if the price reaches your target. This can be particularly useful for more expensive products where waiting for a price drop could save you a meaningful amount of money. Keepa Isn’t the Only Option Keepa is not the only tool available for checking Amazon prices. Two alternatives worth knowing about are: CamelCamelCamel A free Amazon price tracker that provides price-history charts and price-drop alerts. Honey A shopping browser extension that can track prices and provide shopping-related features across supported retailers. Keepa remains one of the more detailed options for analysing Amazon price history, but it’s worth knowing that you have alternatives. Should You Bother Checking Price History? If you regularly shop on Amazon, it’s worth building into your routine. You don’t have to check the price history of every £5 purchase. But for more expensive products — TVs, laptops, phones, power tools, kitchen appliances, headphones, cameras and smart home equipment — checking the historical price takes only a minute and could prevent you from buying at the wrong time. Before purchasing an expensive item, use this quick process: 1. Find the product. 2. Check the current price. 3. Check the historical price. 4. Compare today’s price with the normal range. 5. Check whether it has recently been cheaper. 6. Decide whether you actually need it. 7. Only then decide whether to buy. Final Verdict Amazon’s discount percentage can be useful, but it shouldn’t be the only thing you look at. A product saying “Save 40%” doesn’t automatically mean you’re getting a 40% bargain. Checking the price history gives you a much better idea of what the product normally costs and whether today’s price is genuinely attractive. Next time you see an Amazon “deal”, don’t immediately reach for your wallet. Check the history first. Disclosure Some links on UK Smart Money may be affiliate links. If you purchase something through one of these links, we may receive a commission at no additional cost to you. We only recommend tools and services that we believe can be useful to our readers.
    • Best Big Data SIM Only Deals UK 2026 — No Contract, No Price Rises

      Best Big Data SIM Only Deals UK 2026 — No Contract, No Price Rises

      Tired of eye-watering data prices and mid-contract price hikes? Mozillion has just launched three new SIM only plans — all on 1-month rolling contracts, running on the UK’s best network, with genuinely huge data allowances and no surprise price rises.

      1. 210GB SIM Only — £17/month

      • ✅ 210GB data
      • ✅ Unlimited calls & texts
      • ✅ Inclusive EU roaming
      • ✅ Uncapped 5G speeds on the UK’s best network
      • ✅ 1-month rolling contract — no long-term commitment

      Get this deal →


      2. 260GB SIM Only — £18/month

      • ✅ 260GB data
      • ✅ Unlimited calls & texts
      • ✅ Inclusive EU roaming
      • ✅ Uncapped 5G speeds on the UK’s best network
      • ✅ 1-month rolling contract — no long-term commitment

      Get this deal →


      3. 310GB SIM Only — £19/month

      • ✅ 310GB data
      • ✅ Unlimited calls & texts
      • ✅ Inclusive EU roaming
      • ✅ Uncapped 5G speeds on the UK’s best network
      • ✅ 1-month rolling contract — no long-term commitment

      Get this deal →


      Why Mozillion?

      All three plans run on 1-month rolling contracts — no 12 or 24-month lock-in, and no mid-contract price rises to worry about. If your needs change, you can switch or cancel with just a month’s notice.

      Prices and data allowances are correct at time of writing — check the links above for current availability.


      Disclosure: UKSmartMoney participates in affiliate programmes. We may earn a commission from qualifying purchases at no extra cost to you.
